Quarterly updates HMRC: what sole traders and landlords must do
If you’re a sole trader or landlord with qualifying income above £50,000, sending quarterly updates to HMRC becomes mandatory from April 2026. A quarterly update is a summary of your business income and expenses, sent through Making Tax Digital (MTD) compatible software. It doesn’t replace your annual Self Assessment return.
Three things to do now:
- Check whether your income puts you over the £50,000 threshold on GOV.UK
- Sign up for MTD for Income Tax if you haven’t already
- Choose MTD-compatible software, such as Ledgery, or start a free trial before your first deadline
Table of Contents
- What are HMRC quarterly updates?
- Who needs to send quarterly updates?
- When are the quarterly tax deadlines?
- How do you prepare and send a quarterly update?
- What records do you need to keep?
- What happens if you miss a deadline?
- Should you report more often than quarterly?
- How Ledgery simplifies quarterly HMRC updates
- What the rules actually ask of you
- Get your quarterly updates sorted with less admin
- Sources
What are HMRC quarterly updates?
A quarterly update is a running total. It reports your income and expenses for a set period, but it’s cumulative from the start of the tax year to the end of that update period, not a fresh count each time. HMRC does not see individual receipts or invoices. Your software groups everything into summary totals by category before sending them across.
That cumulative structure matters practically:
- Made a mistake in quarter one? You fix it by adjusting the totals in a later update, not by amending the original submission.
- Each submission gives HMRC (and you) an updated estimate of your tax bill based on the year so far.
Pro Tip: Keep a running note of anything you’re unsure how to categorise. When the next update rolls around, you can fold the correction into the cumulative total instead of scrambling to remember what happened three months earlier.
Who needs to send quarterly updates?
From April 2026, sole traders and landlords with qualifying income above £50,000 must comply with MTD for Income Tax. Qualifying income is based on your gross income before expenses, taken from your most recent Self Assessment return.
A few points worth knowing:
- If you run more than one self-employment business, or own more than one rental property, you submit a separate update for each income source.
- Below the threshold, you can still sign up voluntarily if you want to get ahead of the rules.
- Exemptions exist for specific circumstances. Check your position against the current guidance on GOV.UK rather than assuming you’re covered.
When are the quarterly tax deadlines?
HMRC sets fixed deadlines for standard, tax-year-aligned quarters. If you want to use calendar quarters instead, you must elect that in your software before submitting your first update of the tax year. Once you’ve made the choice, it applies for the rest of that year.
| Quarter type | Period covered | Deadline |
|---|---|---|
| Standard Q1 | 7 May deadline quarter | 7 August |
| Standard Q2 | 7 August deadline quarter | 7 November |
| Standard Q3 | 7 November deadline quarter | 7 February |
| Standard Q4 | 6 April to 5 April | 7 May |
| Calendar option | 1 April to 31 March, in quarterly blocks | Same submission month pattern, aligned to calendar quarters |
Because updates are cumulative, submitting a later one can effectively fulfil an earlier missed obligation. The totals catch up. That doesn’t mean deadlines are optional. It just means a late second-quarter submission that includes first-quarter figures still gets HMRC the data it needs, even if it arrives after the original date.
How do you prepare and send a quarterly update?
Once you’re set up, sending an update to HMRC is mostly a case of checking figures rather than entering them from scratch.
- Keep digital records throughout the quarter. Photos of receipts, bank feeds, and invoices all count, provided your software stores them digitally rather than on paper.
- Let your software build the summary totals automatically from those records, sorted by expense and income category.
- Authorise your software to connect to HMRC, then select the correct business or property source before reviewing the category totals.
- Use the consolidated expenses option if your turnover qualifies. It’s quicker but not suitable for everyone.
- Check the estimated tax figure the software generates, then submit.
HMRC’s own developer documentation notes that the obligation can take up to an hour to be marked as fulfilled in its systems, so don’t panic if your dashboard doesn’t update instantly. Agent guidance also suggests the first submission is the steepest part of the process. Once your software is linked to HMRC, routine quarters tend to take minutes rather than hours.
Pro Tip: Do a dry run with your software’s authorisation step a week or two before your first deadline. Linking accounts sometimes throws up a query from HMRC’s identity checks, and you don’t want that surprise on submission day.
What records do you need to keep?
You need digital records of sales, invoices, receipts, and, for landlords, rental statements. These should cover the full tax year, and HMRC expects them retained for a reasonable period after you file, in line with normal Self Assessment record-keeping practice.
The update itself only ever shows totals by category. Nobody at HMRC reviews your individual invoices unless you’re later asked for evidence.
- Income by source (rent, sales, other business income)
- Expense categories (repairs, travel, professional fees, and so on)
- Bank statements or feeds that back up the totals
If your turnover is below the relevant threshold, you can use the consolidated expenses option, reporting one combined expense figure instead of splitting it into categories. It saves time but gives HMRC less visibility, so weigh that against your own record-keeping habits.
What happens if you miss a deadline?
HMRC has confirmed that no penalty points will apply for late quarterly updates during the first year of MTD for Income Tax, covering the 2026 to 2027 tax year. That’s a genuine grace period, not a permanent exemption.
- From the following year, HMRC’s points-based penalty system applies. Points accumulate for repeated late submissions and eventually trigger a fixed penalty.
- Correcting a mistake doesn’t mean refiling an old update. You include the correction in your next cumulative submission instead.
- If you’re consistently missing deadlines or unsure how to fix a persistent error, it’s worth contacting HMRC directly or bringing in an accountant before points start building up.
Should you report more often than quarterly?
Nothing stops you submitting updates more frequently than the statutory minimum. Some MTD software allows monthly updates if you’d rather keep closer tabs on your tax position throughout the year.
This suits businesses with seasonal or variable income, where a single quarterly snapshot can hide big swings in cash flow. Reporting monthly gives you:
- A more current estimate of tax owed, useful for setting money aside as you go
- Earlier warning of income spikes that might push you over a threshold
- The option to effectively fulfil a quarter’s obligation early, since the cumulative totals still count towards the statutory deadline
It’s extra admin for some, but for others it removes the end-of-quarter scramble entirely.
How Ledgery simplifies quarterly HMRC updates
Ledgery is built around the exact job this article describes: turning receipts and income records into HMRC-ready quarterly summaries without you doing the sorting by hand.
- Snap a photo of a receipt and Ledgery categorises it automatically.
- Income and expenses are organised into the totals HMRC expects, quarter by quarter.
- Deadline alerts flag the 7 August, 7 November, 7 February and 7 May dates before they arrive.
- The first quarter is free, so you can try the full process before committing to a subscription.
Setup and the first submission are usually the hardest part of MTD compliance. Once your records are linked, later updates take minutes rather than hours.
Pro Tip: Start scanning receipts from day one of a new tax year, even before you’re sure you’ll hit the £50,000 threshold. It’s far easier than reconstructing three months of expenses the week before a deadline.
Getting set up early on Ledgery means your first quarterly submission is a formality rather than a fire drill.
Sole traders and landlords above the £50,000 threshold must send cumulative quarterly income and expense summaries to HMRC through MTD-compatible software from April 2026.
| Point | Details |
|---|---|
| Check your threshold | Qualifying income above £50,000 makes MTD quarterly updates mandatory from April 2026. |
| Know your deadlines | Standard quarters fall due 7 August, 7 November, 7 February and 7 May each year. |
| Updates are cumulative | Corrections go into a later update rather than amending an earlier submission. |
| First year has no penalty points | HMRC won’t apply points for late updates during 2026 to 2027, but points-based penalties follow after. |
| Use compatible software | Ledgery scans receipts, builds category totals, and sends deadline alerts, with a free first quarter to try it. |
What the rules actually ask of you
Most of the anxiety around MTD comes from treating quarterly updates like mini tax returns. They aren’t. HMRC wants totals, not documents, and the cumulative structure means an early mistake isn’t a crisis. It gets absorbed into the next submission.
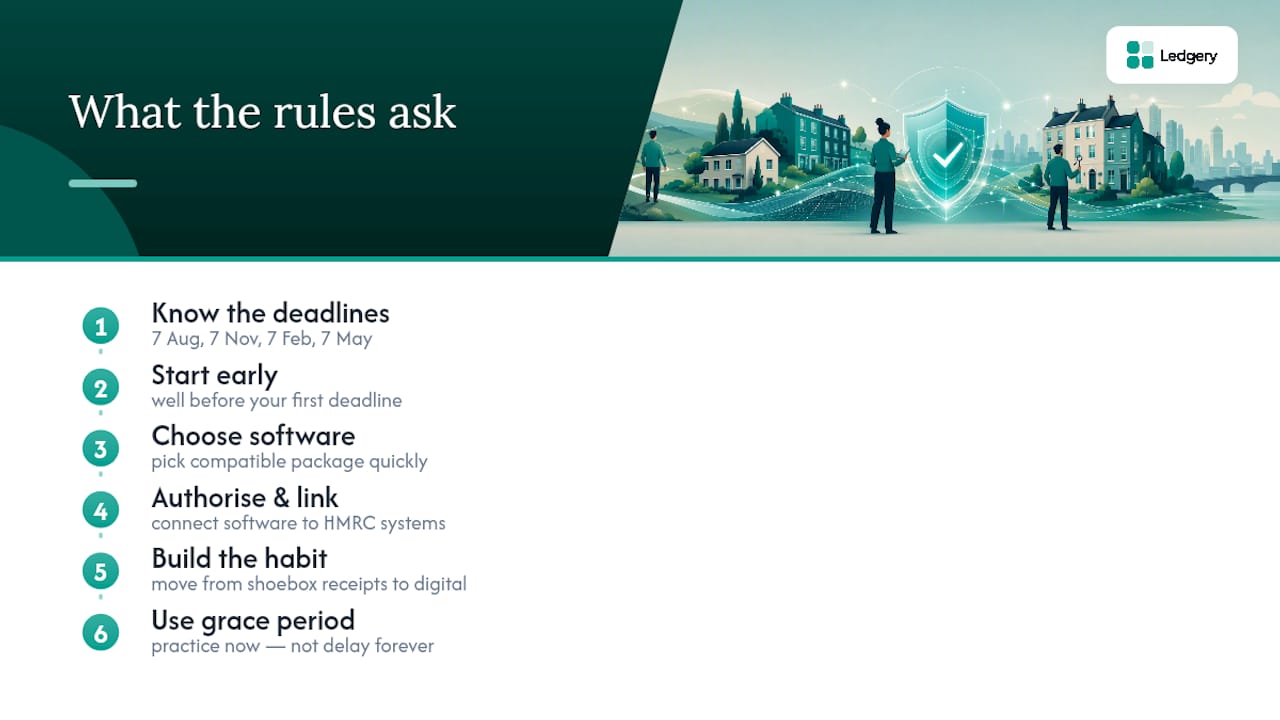
Where conventional advice falls short is in overstating the deadline pressure while understating the setup pressure. The dates themselves, 7 August, 7 November, 7 February, 7 May, are simple once you know them. The real friction sits in the first few weeks: choosing software, authorising it against HMRC’s systems, and building the habit of digital record-keeping instead of a shoebox of receipts.
If you take one thing from this, prioritise getting your records digital and your software linked well before your first deadline, not the week of it. The penalty grace period for 2026 to 2027 is generous, but it’s a one-off. Treat it as time to build the habit, not as licence to leave things until the points system kicks in the following year.
— Jason
Get your quarterly updates sorted with less admin
Ledgery is the practical alternative to manual spreadsheets and shoebox receipts for sole traders and landlords facing MTD for Income Tax. Instead of sorting expenses into categories yourself every quarter, you photograph receipts as they come in and Ledgery organises them into the summary totals HMRC expects.

It suits anyone above the £50,000 threshold who wants deadline alerts rather than a diary reminder, and anyone who’d rather spend an hour a month on receipts than a weekend every quarter. The first quarter is free, so you can see how the categorisation and submission process works before paying anything. If you’ve read this far and you’re still not sure whether your software will be ready for 7 August, start your free trial on Ledgery today and get your first quarter’s records organised before the deadline arrives.
Sources
Recommended
Self-employment and property income in one subscription, first quarter free. Join the early access list and we’ll email you once, when it opens.
Join early access